

The Easiest Ways To Lower Your Health Care Bills
Understanding the complexities of the American healthcare system can sometimes feel like deciphering an ancient manuscript. Just when you think a procedure is covered, you end up with a bill that you can’t afford. You should never have to choose between an important follow-up appointment and paying your mortgage, yet many people are faced with crushing healthcare costs every day. According to the data website USAFacts, which crunched numbers from the Centers for Disease Control (CDC), personal health care spending — defined as goods and services like prescription drugs and hospital care — rose 1,306% from 1980 (when per-person spending was $943) to 2024 (when it hit $3,590 a person). Even adjusting for inflation showed that per-person spending on personal health care was 3.7 times higher by 2024.
Thankfully, there are clever ways to get ahead of your health bills so you end up paying less out of pocket. Follow these tips for lower health care costs every time.
Enroll in an HSA or FSA
HSAs (health savings accounts) and FSAs (flexible spending accounts) are great options for covering medical costs. Essentially, these accounts allow you to set aside pretax money that can be withdrawn later to cover medical bills. These withdrawals are tax-free and can be used for copays, prescriptions, vision exams, dental visits, and more. While health savings options are usually offered by your employer, you can sign up for an HSA even if you’re unemployed, as long as you’re enrolled in a high-deductible health plan. Annual contribution limits for HSAs are $4,400 for individuals and $8,750 for family coverage, and $3,400 per employer for FSAs.
There are a few major differences between HSAs and FSAs, but HSAs allow a lot more flexibility — HSAs belong to you forever, while FSAs are owned by the employer and forfeited if you decide to work elsewhere. With an HSA, you can carry over unused funds year after year, while for an FSA, funds expire at the start of each new benefit year. You can also invest the money in your HSA to generate compound interest over time.
Utilize Tax Deductions
If you pay a substantial amount for medical coverage in a given year, you may be able to write off those charges on your annual tax filing. Visit the IRS website and take a quick 15-minute survey to help you determine whether you’re eligible to deduct your medical bills. Potential deductions include hospital stays, prescription medications, and doctor visits, all of which can lead to a more substantial tax refund.
Stay In-Network
One of the frustrating parts of the health care industry is switching insurances only to find that your lifelong doctor doesn’t accept your new plan. You can either pay out of pocket or cut ties and find a new doctor. While it might be difficult, take the latter option. Ask your doctor if they know of anyone who takes your new insurance or contact your insurance directly for some options. Choosing a provider who takes your insurance plan allows you to have more procedures covered, saving you lots of money in the future.

Reader Favorites
Use Discounted and Generic Prescriptions
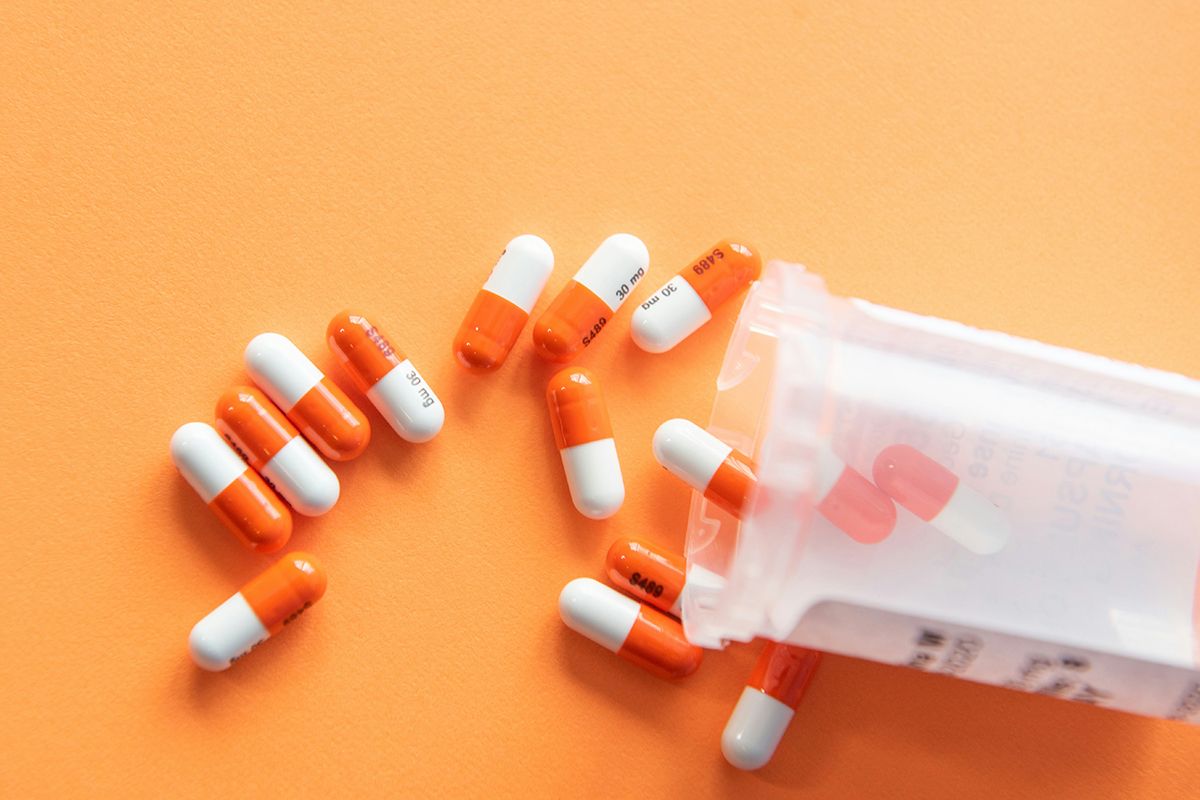
No one should be forced to pay high costs for a necessary prescription, and the good news is that you no longer have to. Generic medications are almost always just as effective and way cheaper than name-brand options, so ask your doctor if they’d be open to prescribing generic medication to help you save. GoodRx and similar companies further help consumers avoid inflated prescription expenses by finding coupons and discounts to ensure the lowest possible cost. You can also ask the pharmacist at your local drugstore if they have a price-matching program or coupons you can use.
Invest in Long-Term Care Insurance
While basic medical insurance covers you in the present, long-term care insurance helps you both plan for the future and save money in the long run. These insurance plans cover the cost of aides, nursing homes, and other expenses that affect us later in life. Planning ahead also helps your loved ones, since they may be responsible for your care in later years.
Reduce Medicare Premiums
If you have Medicare, you may be susceptible to surcharges depending on your income. This concept is called the income-related monthly adjustment amount (IRMAA), and it affects people with a modified adjusted gross income (MAGI) of over $109,000 for individuals and over $218,000 for couples. If you exceed those thresholds, you will end up paying more for Medicare Part B (and, if you’re enrolled, Part D) than you would otherwise.
You can avoid these surcharges with clever money management — putting your wealth into a Roth IRA can help distribute your money so that you remain in a lower tax bracket. Roth accounts are pretaxed and can be invested so your wealth grows over time. When you’re ready to withdraw your contributions, you won’t be taxed or penalized. (Earnings, however, may be a different story, depending on your age and how long you’ve had your account.)
Consider Outpatient Facilities
While certain medical procedures must take place in a hospital, for others it’s fine to visit an outpatient facility instead. Common outpatient services include MRI scans, rehabilitation, and even chemotherapy — it all depends on the individual facility. Outpatient facilities can cost significantly less than hospitals because there’s no need for an overnight stay, and the staff is just as capable.
Avoid the Emergency Room
The average cost of visiting the emergency room in 2025 was $2,715 — a steep price to pay even for those who are financially well-off. Assuming your condition isn’t life-threatening, you should head to an urgent care facility instead. Urgent cares are far cheaper than the ER for both individuals and their insurance providers, but you’ll still get high-quality treatment — and sooner, since the wait time at urgent care centers is often less than that in the ER.
There’s a caveat here, however. While urgent cares might be great for checking out concerning symptoms or injuries, you should head straight to the ER if you are experiencing a true, life-threatening emergency. In the end, your health and safety are more important than saving cash. And if you’re hit with a bill you weren’t expecting — because the doctor you saw for emergency care was out of network, for example — you may be eligible for protections under the federal No Surprises Act.
More From Our Network
Better Report is part of Inbox Studio, an email-first media company. *Indicates a third-party property.


Bennett Kleinman is a New York City-based staff writer for Inbox Studio. He is also a freelance comedy writer, devoted New York Yankees and New Jersey Devils fan, and thinks plain seltzer is the best drink ever invented.
This article is for general informational purposes only.
Affiliate Disclaimer Medical Disclaimer Financial Disclaimer